When a small business asks how to accept Bitcoin payments, the real question is what must happen before, during and after checkout. First define the customer journey and the records you need; then use a best crypto payment gateway comparison as one research input, not an endorsement or a substitute for checking current terms, supported networks and settlement behavior. This guide walks through those decisions in order, including what a small pilot should prove before it becomes a normal payment option.
This is an educational reference, not a current service offer from the former agency associated with this domain. No present-day operator, client, processor partnership or payment capability has been verified. The steps below are general planning questions for a business to resolve with its own provider, accountant and legal adviser.
Before you enable it: decide what problem it solves
A payment method adds another route through checkout. It is useful only if customers can understand it and the business can handle the resulting operational work. Start with a narrow question: are customers asking for Bitcoin specifically, or is the underlying need a different checkout experience, a cross-border option or a way to reduce friction for a particular audience? Those goals are not interchangeable.
Write down the intended customer, product or service, countries involved and what a successful payment looks like. A one-off invoice, an online basket and an in-person point of sale create different requirements. The same is true of a fixed-price sale versus a quote that can change while a customer is deciding. Do not announce support until the business knows which assets and networks it will accept and how it will explain a failed, late or underpaid transaction.
Choose a payment model before comparing providers
Broadly, a business can use a third-party processor that handles some checkout or settlement steps, or control a wallet directly. Product details vary by provider and jurisdiction. This distinction is a starting point for questions, not a complete description of any named service.
| Decision area | Processor-assisted flow | Direct wallet flow |
|---|---|---|
| Setup | May provide checkout tools, invoices or integrations; verify the exact product and supported assets. | The business configures and operates its own receiving workflow and staff procedures. |
| Control | A provider may control conversion, custody or settlement steps described in its terms. | The business takes on more responsibility for keys, access, reconciliation and recovery. |
| Records | Export and reconcile provider reports with orders and accounting records. | Match wallet transactions to orders using a documented process without exposing sensitive wallet data. |
| Failure handling | Confirm how expiry, underpayment, overpayment, refunds and support escalation work. | Write and test those procedures before offering the option. |
Compare the same concrete items for either model: supported asset and network, quoted exchange rate and expiry, transaction or service fees, confirmation policy, settlement currency and timing, geographic availability, account controls, data handling, customer support, exportable records and refund procedure. Read current terms directly. A feature list or marketing page does not establish whether a service fits a particular business.
Map what happens at checkout
A reliable workflow makes each handoff visible. Decide who creates the payment request, what amount and network the customer sees, how long a quote remains valid, how the business learns funds arrived and who may fulfill the order. If a processor is involved, document which steps the provider performs and which remain the merchant’s responsibility.
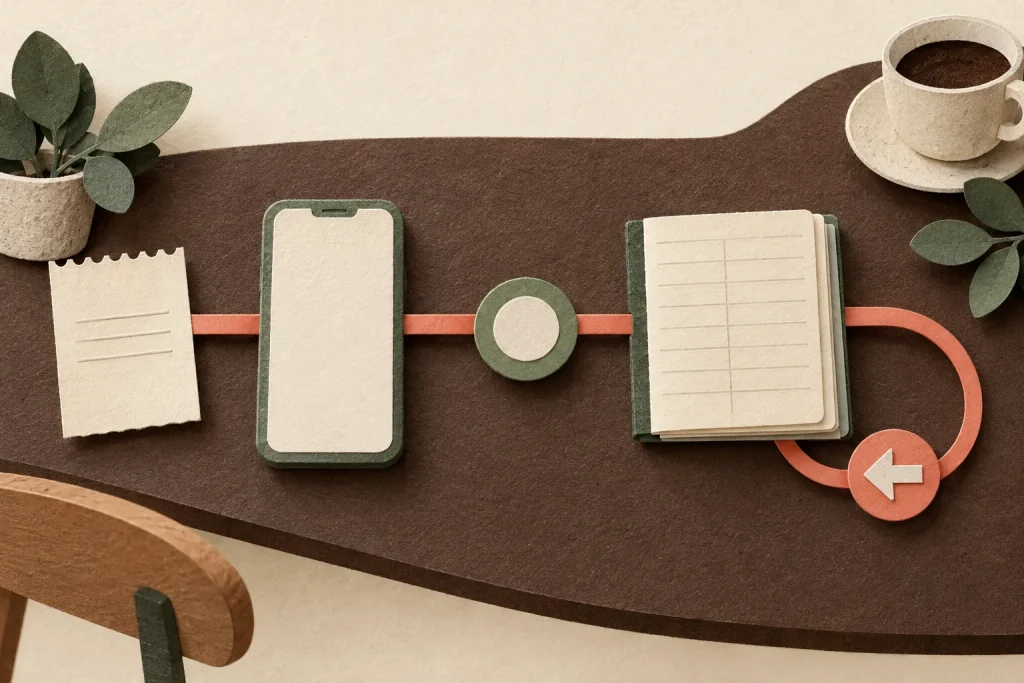
Conceptual artwork: an order moves through payment confirmation, records and a refund path. Actual steps depend on the wallet, network and provider.
- Price the sale. Keep the product price and payment amount distinct in the order record. If a provider converts a displayed fiat price into a digital-asset amount, note the quote time and expiry rules.
- Present exact instructions. Name the asset and network clearly. Explain the time limit and what to do if a quote expires. Never ask a customer for a private key or recovery phrase.
- Set a fulfillment threshold. Confirm whether the business waits for a processor event, a network confirmation or another provider-defined status. Do not treat a screenshot or a customer’s message as proof of settlement.
- Reconcile the order. Store the order ID, time, quoted amount, received status, fees and settlement record needed by the business. Restrict access and keep only customer information needed for the transaction.
- Close the exception path. Decide how staff respond to late, wrong-network, partial or duplicate payments, cancellations and refund requests. Explain the policy before checkout.
Network status names, confirmation behavior, quote windows, conversion and refunds differ. Use the payment provider’s current documentation for product-specific steps, and test the exact checkout customers will see.
Records, refunds and security are part of the payment
Receiving a digital asset does not remove the need for ordinary sales records. The U.S. Internal Revenue Service says taxpayers should keep records sufficient to support their tax positions, including records for digital-asset receipts and fair market value. The details depend on the business and tax situation; review current IRS guidance and ask a qualified tax professional how it applies. IRS virtual-currency transaction FAQs.
Refunds need a written rule because a blockchain transfer is not the same as reversing a card charge. State whether the business refunds in the original asset or another agreed form, who verifies the destination, which exchange-rate timestamp is used if relevant and what information is retained. Have a second person review any high-risk change to a refund address or wallet procedure. Never put private keys, seed phrases or recovery secrets into customer-service notes.
Use the same care with customer data as any checkout: collect only what is needed, limit staff access, secure accounts and check the provider’s data practices and incident process. The Federal Trade Commission’s small-business cybersecurity guidance covers account protection, software updates, data handling and vendor security. FTC cybersecurity guidance for small businesses.
A practical launch sequence
- Ask intended customers and document the actual checkout need.
- Choose a processor-assisted or direct-wallet model; do not mix both in the first test.
- Review current terms, fees, supported assets and networks, settlement, account security, exports and support.
- Write customer instructions, quote-expiry messages, fulfillment thresholds and refund policy.
- Ask the business accountant and legal adviser to review recordkeeping and jurisdiction-specific obligations.
- Run controlled test transactions using the provider’s supported test process, then rehearse late, failed and refund cases with staff.
- Launch only to the intended audience, monitor exceptions and pause if staff cannot resolve a failure safely.
Before expanding, measure operational outcomes rather than promotional ones: completed versus abandoned requests, reconciliation time, exception rate, support questions and refund completion. Define the measurement window and denominator before comparing periods. A small pilot can reveal workflow problems; it cannot prove future demand or guarantee lower costs.
Frequently asked questions
Can a small business accept Bitcoin without a payment processor?
Some businesses choose to manage a receiving wallet directly, but that transfers setup, access control, reconciliation, security and recovery responsibilities to the business. Whether it is appropriate depends on the business, its jurisdiction and its capabilities.
Does a Bitcoin payment automatically count as final at checkout?
Not necessarily. Follow the confirmation and settlement rules of the wallet, network service or payment processor actually used, and tell customers what status is required before an order is fulfilled.
How should a business handle a Bitcoin refund?
Publish the refund process before accepting payment. Specify who approves it, what asset or amount is returned, how the destination is verified and how the transaction is recorded. Get professional advice where consumer or tax rules apply.
Does this guide recommend a gateway?
No. It provides a neutral checklist for comparing current terms and workflows. The linked comparison is a research starting point, not proof of suitability, endorsement or affiliation.
Scope and source notes
This page explains general operational questions and is not legal, tax, investment or accounting advice. Rules, provider features and network behavior can change. The former business history of this domain is separate from this guide: no current agency service or Bitcoin-payment capability is claimed. For how the reference handles dated records and uncertainty, see the source method and editorial standards.